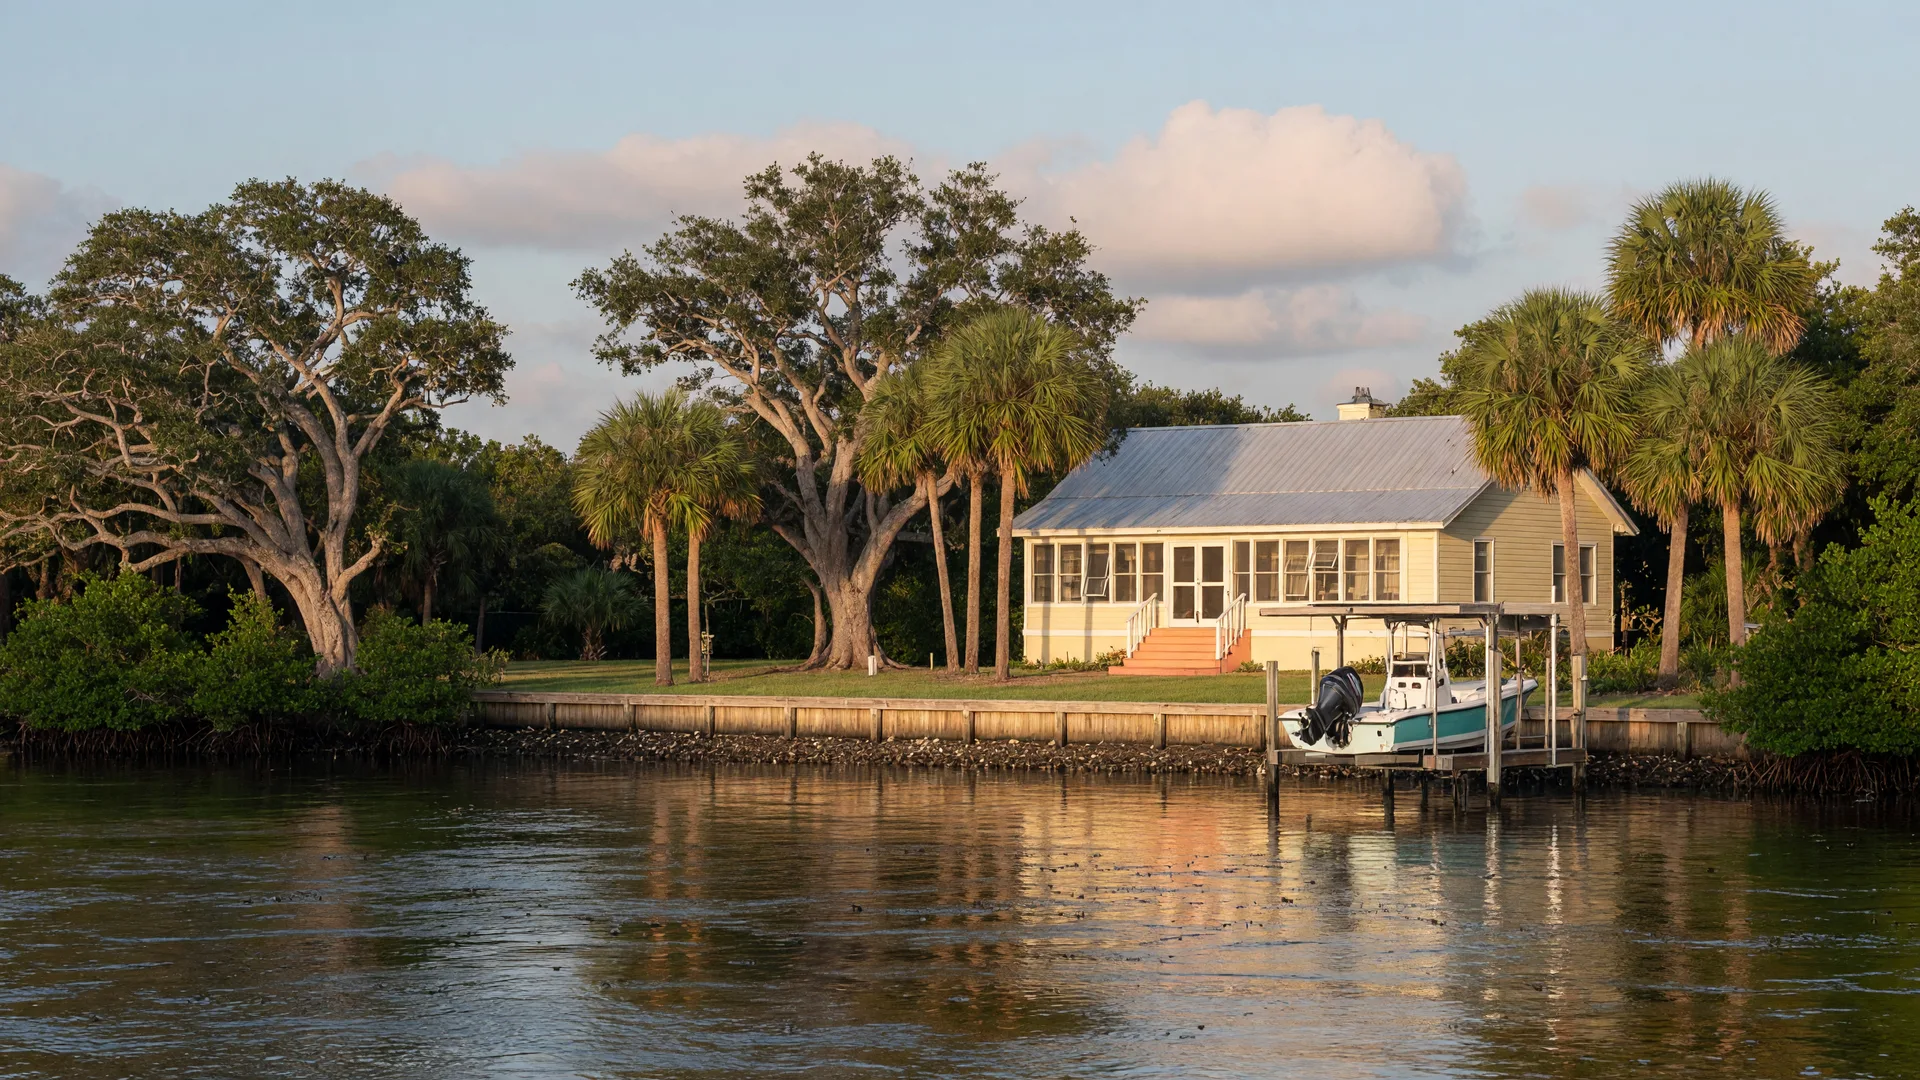
If you're looking at waterfront homes on the Nature Coast, the same fear comes up every time: the flood insurance. Buyers fall in love with the dock, the sunset, the Gulf access. And then they see the flood zone designation and freeze. Here's what I tell every waterfront buyer, in plain English.
What a flood zone letter actually means
A flood zone isn't a verdict on the house. It's a risk rating on the land, drawn from FEMA's flood maps, and those maps have known imperfections. Some homes in high-risk zones have never flooded; some outside them have. The zone tells you what insurance will cost, not whether the home is worth buying. What matters is getting a determination AND a real quote before you fall too far in love.
NFIP vs private flood insurance
Here is the short version of the two routes to a flood policy, and what each one means for your wallet:
-
Standard homeowners insurance does NOT cover flood damage. It's always a separate policy.
-
The federal program (NFIP) is the classic route, but it carries a 30-day waiting period before coverage starts.
-
Private flood insurance often costs less, covers more, and can start in as little as 14 days.
-
Your lender may require flood coverage if the home is in a high-risk zone, but that doesn't lock you into any one policy. Shop both.
The move that can save you thousands: an assumable policy
Some waterfront sellers carry a flood policy that a buyer can simply take over. That's a quiet gem. For example, my current listing at 12612 4th Isle in Leisure Beach comes with an assumable flood policy at $3,821 per year. A known, locked-in cost the next owner can step right into, instead of pricing a brand-new policy at today's rates. When you see "assumable flood insurance" in a listing, ask about it. It's a real dollar-and-cents advantage.
Your 3-step waterfront insurance plan
- 1
Get the flood zone determination AND a quote from both NFIP and a private carrier before you make an offer.
- 2
Factor the premium into your monthly budget like property taxes. It's a line item, not a surprise.
- 3
Ask the seller's agent whether the current policy is assumable.
Flood insurance shouldn't be the reason you talk yourself out of the waterfront life you want. With a little translation and the right numbers, it's just part of the plan. If you're looking on the water, or you're already under contract and second-guessing the insurance part, text or call me anytime. I'm happy to walk you through it.
Questions about a waterfront purchase? Text or call Kathleen at (484) 866-6543, or book a chat online. She'll walk you through the flood insurance numbers before you make an offer.
See you on the water,
Kathleen